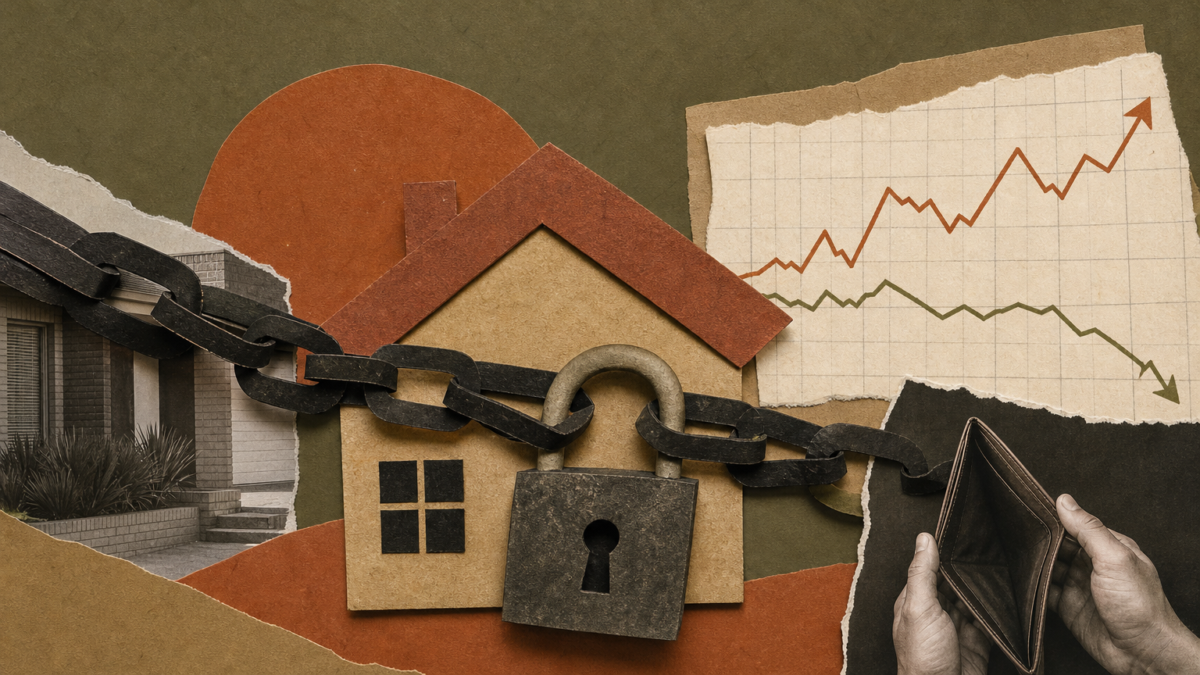
In what is proving to be one of the most challenging property cycles in modern Australian real estate, declining house prices are failing to offer the reprieve home seekers have been waiting for.
Instead, a punishing combination of elevated interest rates, persistent inflation, and strict bank serviceability testing has created a sharp disconnect between lower listing valuations and actual buyer purchasing power.
Data compiled by financial comparison platform Canstar and published by realestate.com.au reveals that despite market corrections across major capitals, the baseline salary required to secure a mortgage on an average Australian home has blown past real-world wage growth.
While the average full-time pay packet grew by roughly $3,600 over the past year, the income threshold needed for standard bank loan approval jumped by an average of more than $30,000 across the capital cities over the exact same period.
Essentially, the qualifying income required by lenders is climbing about eight times faster than wage growth.
Ground zero for this affordability squeeze remains Sydney, where hopeful purchasers must now command a gross household income of approximately $245,000 to clear bank mortgage stress tests and secure a median-priced home with a standard 20 per cent deposit – an $11,000 increase over last year.
Smaller markets are experiencing similar structural pressure.
In Brisbane, the income required to purchase an average house has climbed to $185,000, representing a $25,000 annual bump for the same asset class.
Meanwhile, Melbourne couples face a market where rising serviceability hurdles have effectively locked them out of 62 additional suburbs compared to twelve months ago.
Analysing the figures, Canstar research manager Josh Sale emphasised that borrowing power is shrinking at a far faster pace than property values are adjusting downward.
He noted that declining borrowing power forces buyers to command significantly higher salaries just to qualify for cheaper homes, while persistent inflation continues to erode their deposit savings capacity.
Industry bodies point out that central bank tightening and policy settings are creating unintended bottlenecks on the ground.
Master Builders NSW chief executive Matthew Pollock highlighted the core contradiction facing agencies and developers, noting that Australia is witnessing a scenario where property values are falling while genuine affordability fails to improve, illustrating how difficult it remains for buyers to clear mandatory bank buffers.
For real estate professionals, this market dynamic is visibly shifting the composition of active buyers.
Unassisted first-home buyers are becoming an endangered species across major capitals, with successful transactions at median price points now heavily dominated by buyers who can leverage equity from existing property or rely on parental financial support.
As lending parameters remain tight, agents and advisors must adapt to a market where buyer interest and vendor price reductions are continually constrained by strict borrowing caps.